The IRS small-business guide points solo founders to mileage, estimated tax, self-employment tax, contractor reporting, and accounting-method checks that can change cash flow and compliance risk in 2026.
What matters for solo founders
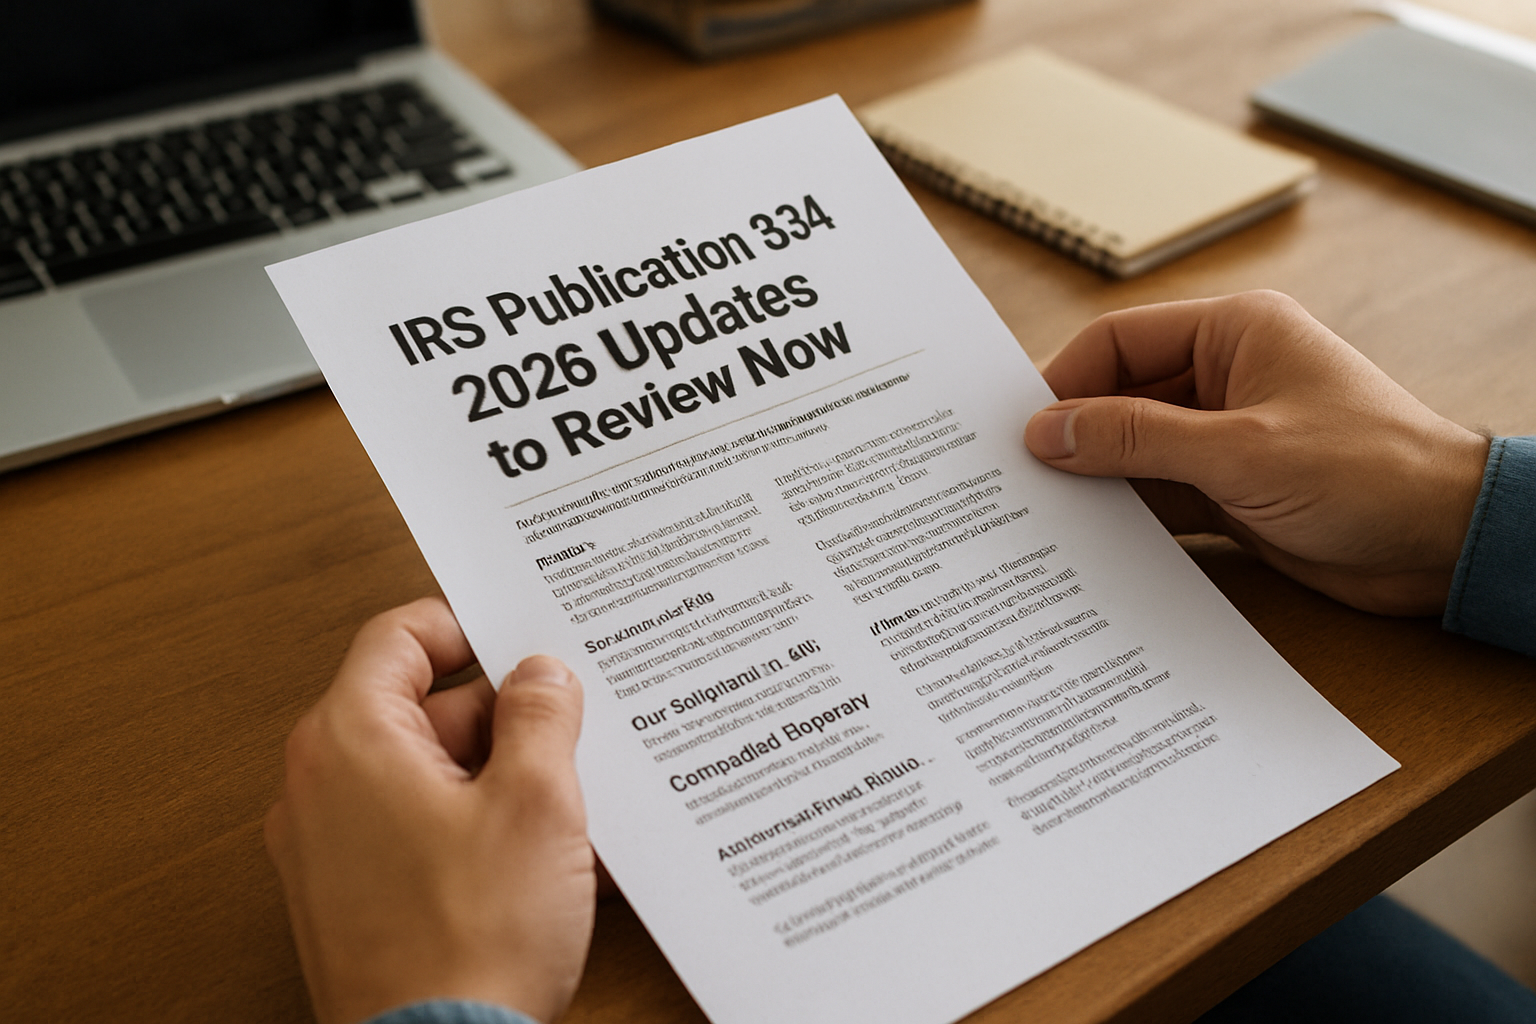
IRS Publication 334 is the IRS’s small-business tax guide for sole proprietors and statutory employees. The IRS page currently shows the 2025 edition, and the IRS directory lists the publication in multiple formats with 2026 postings of the 2025 edition. That means the practical move for small-business owners is not to wait for a separate 2026 booklet, but to use the current Pub. 334 framework as a 2026 planning checklist.
The business value is straightforward: the guide highlights the tax items most likely to affect cash flow, deductions, and filing risk for solo operators. For founders who drive for sales calls, deliveries, client work, or field service, mileage tracking remains a real deduction lever. The verified IRS mileage rates for 2026 are 72.5 cents per mile for Jan. 1 through June 30, 2026, and 76 cents per mile for July 1 through Dec. 31, 2026. If your records are weak, that deduction can disappear in practice even when the business use is real.
Deduction and payment items to review now
Pub. 334’s 2025 “What’s New for 2026” language says the excess business loss disallowance is permanently extended and the 20% qualified business income deduction is permanent for qualified active trades or businesses. For owners, that means tax planning should not assume those rules are temporary. It also means entity and income planning still matter, because the guide continues to frame QBI as a live issue for eligible businesses rather than a one-time tax break.
The same IRS material says the information-reporting threshold for certain payees rises to $2,000 for reportable payments made after 2025. For small businesses that use contractors, that is a bookkeeping and vendor-management issue, not just a tax footnote. Payment systems, W-9 collection, and 1099 workflows should be reviewed before year-end so reporting does not become a scramble after payments are already made.
Publication 334 also points owners to estimated tax payments, EFTPS, Schedule SE, Form 1099-NEC, Form 1099-MISC, Form 8300, accounting methods, inventory rules, and disposition of business property as core compliance areas. That is useful because these are the places where small businesses most often leak cash or create avoidable penalties: missed estimated payments, misclassified contractors, poor inventory tracking, or bad records when selling business property.
Self-employment tax and quarterly cash flow
For 2026 planning, the verified research brief says the maximum net self-employment earnings subject to Social Security tax is $184,500. That matters for founders who have both W-2 wages and Schedule C income, because the wage base affects how much of the year’s earnings are exposed to Social Security tax. Pub. 334 also directs readers to self-employment tax rules and social security coverage, which makes this a cash-flow item, not just a filing item.
The IRS small-business guidance also notes that self-employment tax generally applies at $400 or more of net earnings, and that estimated tax payments are required when tax due is expected to be $1,000 or more under the relevant instructions. For solo founders, that means the safest move is to update quarterly projections before the year gets away from you. Underpaying estimated tax can create a penalty, while overpaying ties up cash that could be used for inventory, ads, software, or payroll.
Operational checklist for 2026
Use the publication as a systems audit. Review mileage logs now so every business trip is captured. Recheck contractor payment workflows so 1099 reporting is ready for the higher threshold. Revisit accounting methods and inventory treatment, because Pub. 334 flags small-business taxpayer exceptions and method-change procedures. If you sell business property, the guide also points to disposition rules, which can affect gain or loss reporting and the timing of tax.
For BizTipper readers, the opportunity is not just compliance. Better mileage capture, cleaner contractor records, and more accurate estimated-tax planning can directly save money, reduce penalty risk, and free up time that would otherwise be spent fixing books later. Pub. 334 is essentially a reminder that tax systems are business systems.