Small employers may be able to turn child-care support into a larger tax-advantaged retention tool starting with expenses paid or incurred after Dec. 31, 2025.
Why this matters for small employers
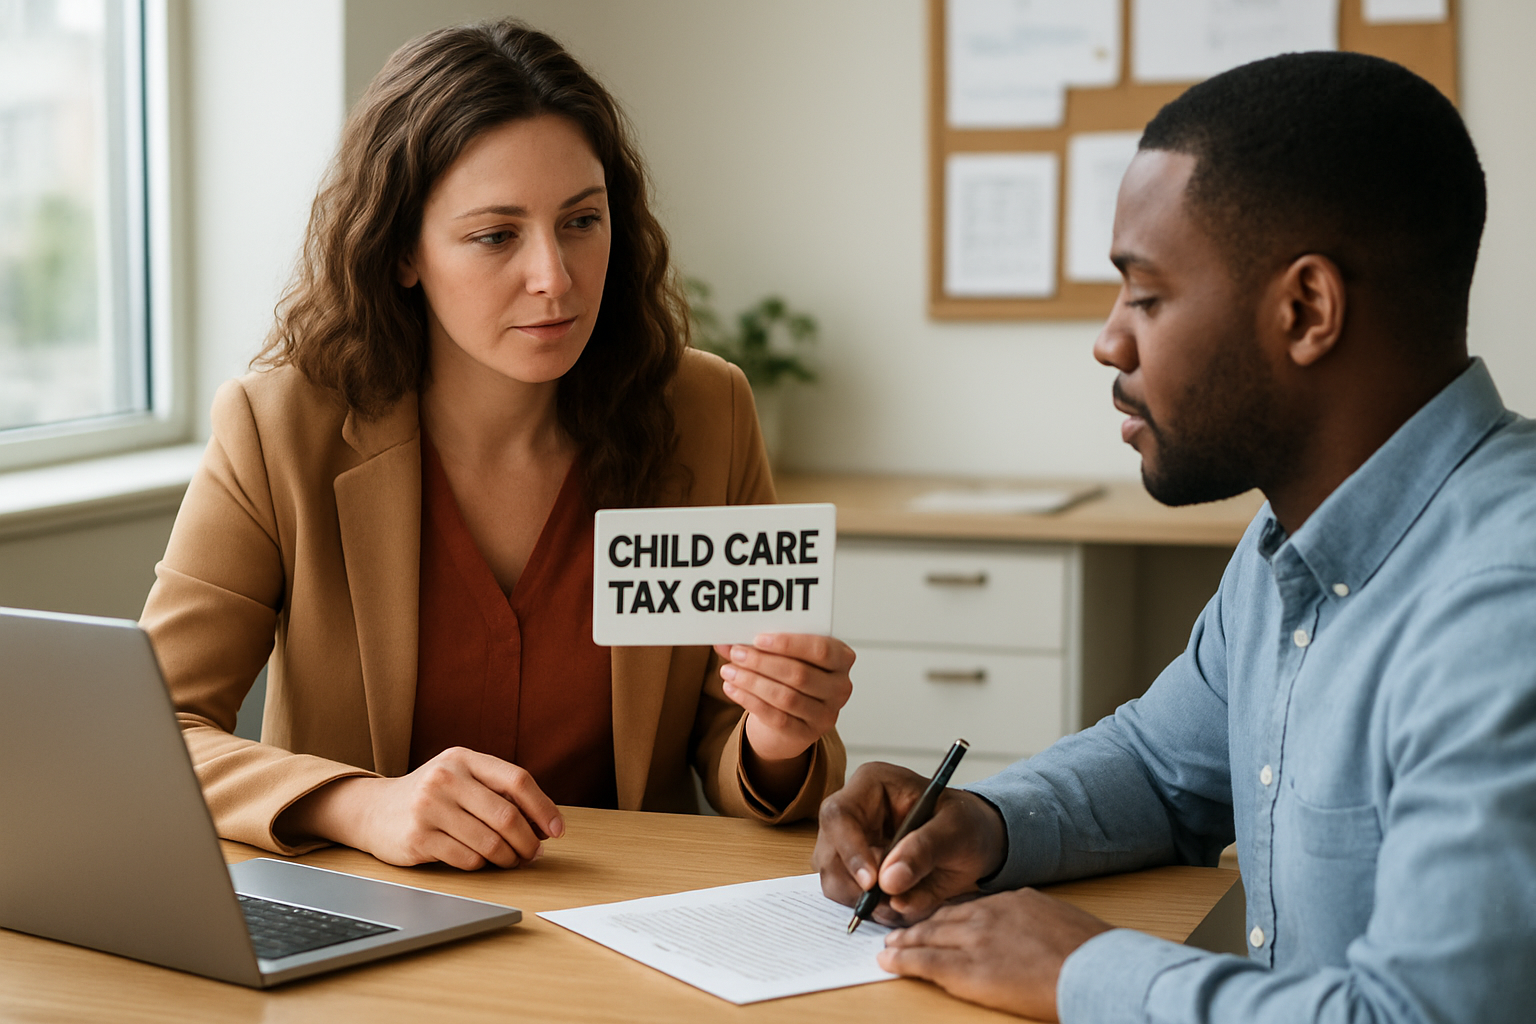
The IRS has updated the employer-provided child care credit for tax years beginning after Dec. 31, 2025, and the change is more than a tax footnote for small businesses. Under the revised Section 45F rules, child-care support can become a practical hiring and retention lever for employers that struggle with attendance, turnover, or recruiting in hourly and frontline roles.
According to the IRS, the enhanced credit applies to qualified child care expenditures and qualified child care resource-and-referral expenditures paid or incurred with respect to employees. That means the credit may help offset the cost of on-site child care, contracted child care services, or referral and navigation support, if the arrangement meets IRS requirements.
What changed in the credit
The IRS says the base credit rises from 25% to 40% of qualified child care expenditures, and to 50% for an eligible small business. The annual cap also increases from $150,000 to $500,000, or $600,000 for eligible small businesses, with inflation adjustments beginning after 2026.
For BizTipper readers, the business significance is straightforward: a benefit that was once a niche tax incentive now has a much larger ceiling. That makes it more realistic for smaller employers to consider child-care support as part of a compensation package rather than as a standalone perk.
Who can use the small-business rate
The IRS defines an eligible small business as one that meets the Section 448(c) gross-receipts test over the preceding five-year period. For taxable years beginning in 2026, the average annual gross receipts test is generally no more than $32 million. That threshold matters because it unlocks the higher 50% credit rate and the larger cap.
The IRS also says a qualified child care facility must be used principally to provide child care assistance and must comply with applicable state and local licensing laws. Under the post-2025 amendments, a qualified facility can also be jointly owned or operated by the taxpayer and other persons for purposes of the credit.
How small businesses can turn this into an operating advantage
The opportunity is not just tax savings. Employers that can help workers solve child-care problems may improve schedule reliability, reduce absenteeism-related disruptions, and strengthen retention. That is an inference from the IRS rules and the function of the credit, not a claim made directly by the IRS.
The planning window is now. The IRS says the enhanced credit applies to amounts paid or incurred after Dec. 31, 2025, so 2025 is the time to evaluate whether a business should contract with a licensed provider, explore a shared-facility model, or build a referral arrangement that fits the rules. Businesses should also document pricing carefully, because the IRS says qualified child care expenditures do not include amounts above fair market value.
For small employers that compete for workers on tight margins, this credit could help convert a costly pain point into a structured benefit with a tax offset. The practical move is to review eligibility, confirm licensing and facility requirements, and map the benefit against hiring and retention goals before 2026 begins.